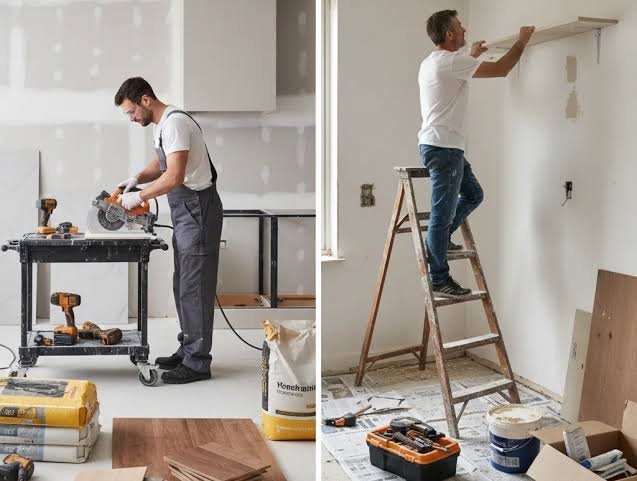
Category: Home Improvement

  • DIY vs Professional Home Improvement: What to Hire Out

    DIY vs Professional Home Improvement: What to Hire Out

    YouTube makes everything look easy. Watch enough renovation videos and you start believing you can retile a bathroom in a weekend. Then reality hits somewhere around hour three, and you’re standing in a half-finished mess wondering where it went wrong.

    The DIY vs professional home improvement decision isn’t really about skill level alone — it’s about knowing which tasks genuinely reward the effort and which ones just aren’t worth the risk.

    How Do You Decide What to DIY and What to Hire Out?

    Quick answer: In the DIY vs professional home improvement decision, tasks involving electrical wiring, gas lines, structural changes, or major plumbing should always go to licensed professionals, while cosmetic work like painting, minor repairs, and basic assembly are generally safe and cost-effective to DIY.

    1. Tasks That Are Genuinely Safe to DIY

    • Painting walls and touch-ups
    • Installing shelving or basic furniture assembly
    • Changing light fixtures (with power off, obviously)
    • Minor caulking and grout touch-ups
    • Basic garden landscaping

    These tasks have low risk if something goes wrong, and honestly, doing them yourself teaches you a lot about your own home in the process.

    2. Tasks That Should Always Go to Professionals

    1. Electrical wiring and panel work — genuine fire and safety risk
    2. Gas line connections or appliance installation
    3. Structural changes, including load-bearing wall removal
    4. Major plumbing involving main water lines
    5. Roof work beyond minor patching

    Quick answer: Electrical and gas-related work should never be attempted as DIY projects, regardless of how simple online tutorials make them look, since even small mistakes can create serious safety hazards affecting the entire home.

    3. The Cost Savings Reality Check

    DIY can genuinely save 30-50% on labour costs for simpler projects. But factor in your own time, the cost of tools you might need to buy, and the risk of mistakes requiring professional correction — sometimes the “savings” shrink considerably once you account for all of this honestly.

    4. Tasks in the Grey Zone

    Some projects sit in between — tiling, basic carpentry, minor plumbing fixes. These depend heavily on your actual skill level and comfort with the specific task, not a blanket rule.

    • Tiling: doable with patience, but uneven results are common for beginners
    • Basic carpentry: reasonable for simple shelving, riskier for load-bearing furniture
    • Minor plumbing: fine for tap washers, risky for anything involving pipe joints

    5. What Skipping Professional Help Actually Costs You

    Picture a homeowner who DIY’d bathroom tiling to save money, only to have water seepage issues within a year from improper waterproofing underneath. The “savings” ended up costing more than hiring a professional would have, plus the hassle of redoing the work.

    6. Tools and Time Investment Worth Considering

    Before committing to DIY, honestly assess whether you already own the necessary tools or would need to buy them. A one-time project might not justify a ₹5,000 tool purchase you’ll rarely use again.

    7. When DIY Genuinely Makes Sense

    • You have relevant prior experience with similar tasks
    • The task has low consequences if done imperfectly
    • You have realistic time availability to do it properly, not rushed

    FAQs

    Q: What home improvement tasks save the most money when done DIY? Painting and minor cosmetic repairs typically offer the best savings-to-risk ratio for DIY projects.

    Q: Is it ever worth hiring a professional for painting? For large exterior jobs or intricate detail work, yes — professionals work faster and often achieve a more even finish.

    Q: Can I install a ceiling fan myself? Only if you’re comfortable safely turning off power at the breaker; otherwise, hire an electrician for this task.

    Q: What’s the biggest mistake people make attempting DIY home improvement? Underestimating the complexity of tasks that look simple in tutorials, particularly plumbing and electrical work.

    Q: How do I know if a wall is load-bearing before attempting DIY changes? You genuinely can’t tell reliably without professional assessment — always consult a structural engineer before touching any wall.

    Conclusion

    The DIY vs professional home improvement decision comes down to honest self-assessment about risk, skill, and true cost savings. Handle the cosmetic, low-risk tasks yourself with confidence, but don’t hesitate to hire out anything involving electrical, gas, structural, or major plumbing work — the money saved isn’t worth the potential safety risk or costly do-overs. [link to related guide on home improvement loan here]

    Alt text suggestions:

    1. “Homeowner painting a wall as a DIY home improvement project”
    2. “Licensed electrician working on home wiring panel”
    3. “Comparison of DIY tools versus professional contractor equipment”
  • Home Improvement Loans: How to Finance Your Renovation

    Home Improvement Loans: How to Finance Your Renovation

    Renovation dreams have a funny way of outpacing bank balances. You want that kitchen redone, maybe a new bathroom, and suddenly the number staring back at you is a lot bigger than what’s sitting in your savings account.

    That’s exactly where a home improvement loan comes in. It’s not the only option, but for a lot of homeowners in 2026, it’s genuinely the most practical way to bridge that gap without draining every rupee of savings.

    What Exactly Is a Home Improvement Loan?

    Quick answer: A home improvement loan is an unsecured or secured personal loan specifically meant for renovation, repair, or upgrade work on your home, typically offering faster approval than a home loan top-up but at a somewhat higher interest rate.

    1. Types of Home Improvement Loans Available

    • Unsecured personal loans marketed specifically for renovation
    • Home loan top-up, if you already have an existing home loan
    • Loan against property, for larger renovation budgets
    • Credit card EMI options, for smaller, quick fixes

    2. Interest Rates You Can Expect in 2026

    Unsecured home improvement loans typically carry interest rates between 10.5% and 16%, depending on your credit score and the lender. Home loan top-ups are usually cheaper, often in the 8.5-10% range, since they’re secured against your existing property.

    Quick answer: Home loan top-ups generally offer lower interest rates than standalone home improvement loans, since the lender already holds your property as collateral, reducing their risk compared to an unsecured loan.

    3. Eligibility Criteria Most Lenders Check

    • Credit score, ideally above 700 for the best rates
    • Stable income, salaried or self-employed with proof of consistent earnings
    • Existing debt-to-income ratio, since lenders don’t want your EMIs stacking too high

    4. Documents You’ll Typically Need

    1. Identity and address proof
    2. Income proof — salary slips or ITR for self-employed applicants
    3. Property documents, if applying for a secured loan
    4. Renovation estimate or quotation from your contractor, sometimes required

    5. How Much Can You Actually Borrow?

    This varies significantly by lender and loan type, but unsecured home improvement loans generally range from ₹50,000 to ₹40 lakhs, while home loan top-ups can go higher depending on your existing loan and property value.

    6. Comparing Top-Up Loans vs Fresh Personal Loans

    Picture two homeowners — one already has an ongoing home loan with a good repayment record, the other doesn’t. The first genuinely has an easier, cheaper path through a top-up loan. The second will likely end up with a standalone personal loan at a somewhat higher rate.

    7. Tax Benefits Worth Knowing About

    Quick answer: Interest paid on a home improvement loan used for repair or renovation of a self-occupied property can qualify for tax deduction under Section 24(b), up to ₹30,000 annually — a detail many homeowners overlook when comparing financing options.

    8. Common Mistakes to Avoid

    • Borrowing more than the actual renovation needs, just because it’s approved
    • Not comparing processing fees across lenders, which can add up
    • Ignoring prepayment penalty clauses if you plan to close the loan early

    Should You Even Take a Loan for Renovation?

    Not every renovation needs financing. For smaller projects under ₹1-2 lakhs, it’s often worth saving up over a few months instead of paying loan interest. For larger structural work, a loan genuinely makes more financial sense than delaying necessary repairs.

    A Simple Decision Checklist

    1. Do you have an existing home loan? Check the top-up option first
    2. Is the renovation urgent (structural, safety-related)? Financing makes sense
    3. Is it purely cosmetic and under ₹2 lakhs? Consider saving instead

    FAQs

    Q: What’s the maximum tenure for a home improvement loan? Typically 5-15 years depending on loan type, with unsecured personal loans usually capped shorter than home loan top-ups.

    Q: Can I get a home improvement loan with a low credit score? It’s possible but expect higher interest rates or the need for a co-applicant with stronger credit history.

    Q: Is a home loan top-up better than a personal loan for renovation? Generally yes, if you already have a home loan, since top-ups offer lower interest rates due to existing collateral.

    Q: Do I need to submit renovation estimates to get the loan approved? Some lenders require this, especially for larger loan amounts, while smaller unsecured loans may not ask for detailed quotations.

    Q: How long does home improvement loan approval typically take? Unsecured personal loans can be approved within 24-72 hours; home loan top-ups may take slightly longer due to property verification.

    Conclusion

    A home improvement loan can genuinely make sense when the renovation is necessary and the numbers work out favourably against your existing savings and debt situation. Compare top-up options against fresh personal loans first, check the tax benefit angle, and avoid borrowing more than your actual project needs. [link to related guide on bathroom renovation ideas here]

    Alt text suggestions:

    1. “Homeowner reviewing home improvement loan documents with a lender”
    2. “Renovation budget planning with loan calculator on laptop”
    3. “Contractor providing renovation quotation for loan application”